You May Be Paying for Data You Never Use
Your phone plan is easy to set once and ignore for years. Your usage is not. Compare the two and you may find you are paying for data, add-ons, or a tier you no longer need.
We’ve been plugging leaks that fire whether you act or not. A phone plan is a recurring charge that can sit untouched long after your usage changes. That makes it worth auditing like any other subscription.
The gap between what you pay for and what you use
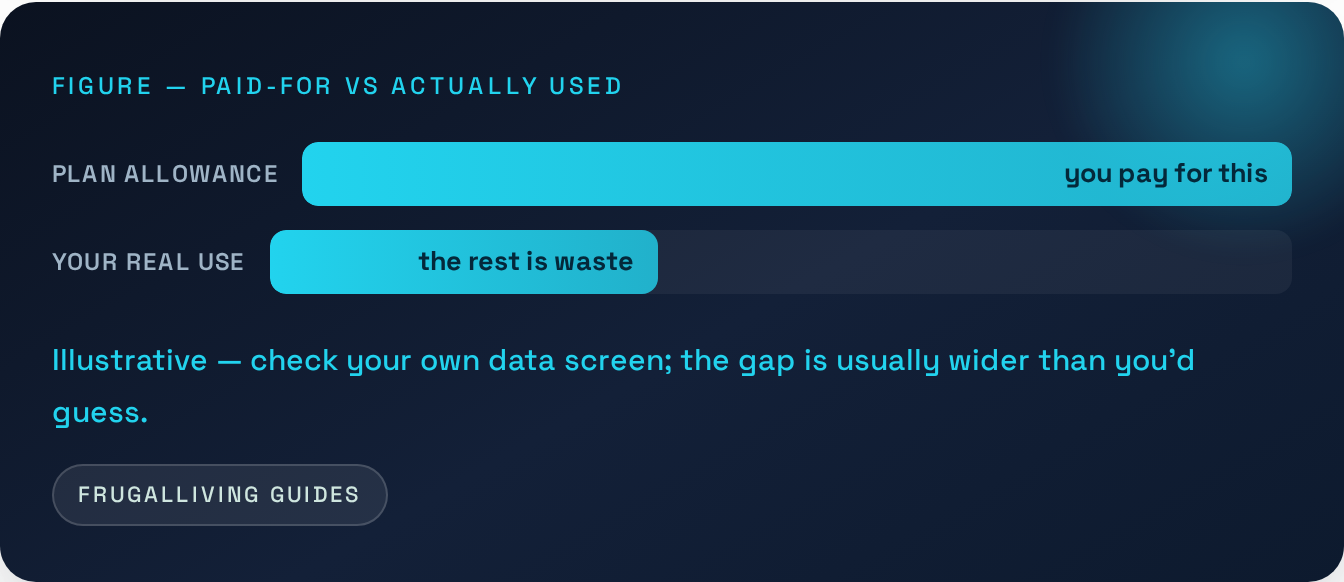
Open your phone’s data usage screen and look at your real monthly number. Now look at your plan’s allowance. If the allowance is consistently far above your real usage, a smaller tier may be enough. The key is to compare several months, not one unusually light month.
Unlimited plans can be useful, but they can also become a default you stop questioning. If much of your usage happens on Wi‑Fi, your actual cellular demand may be lower than the plan you chose years ago.
The traps that keep the gap open
Three things commonly keep the gap open:
- Overage assumptions. Do not assume an old overage experience still matches your current plan. Some carriers slow data after a threshold; others charge differently. Check the actual terms before paying for extra capacity “just in case.”
- Bundled extras you don’t use. Device insurance, streaming add-ons, “premium” perks quietly ride along on the bill. Each feels small; together they’re a second plan.
- Plan inertia. A plan can become poor value simply because the market changed while you stayed put. Compare current offers instead of assuming tenure earns the best price.
Right-size it once
The fix is a fifteen-minute audit, not a lifestyle:
- Read your real usage over the last 3 months from your phone’s settings. Take the highest month, not the average, as your target — then choose the smallest plan that clears it.
- Strip the bundles you don’t actively use. If you can’t remember using it, you’re insuring nothing.
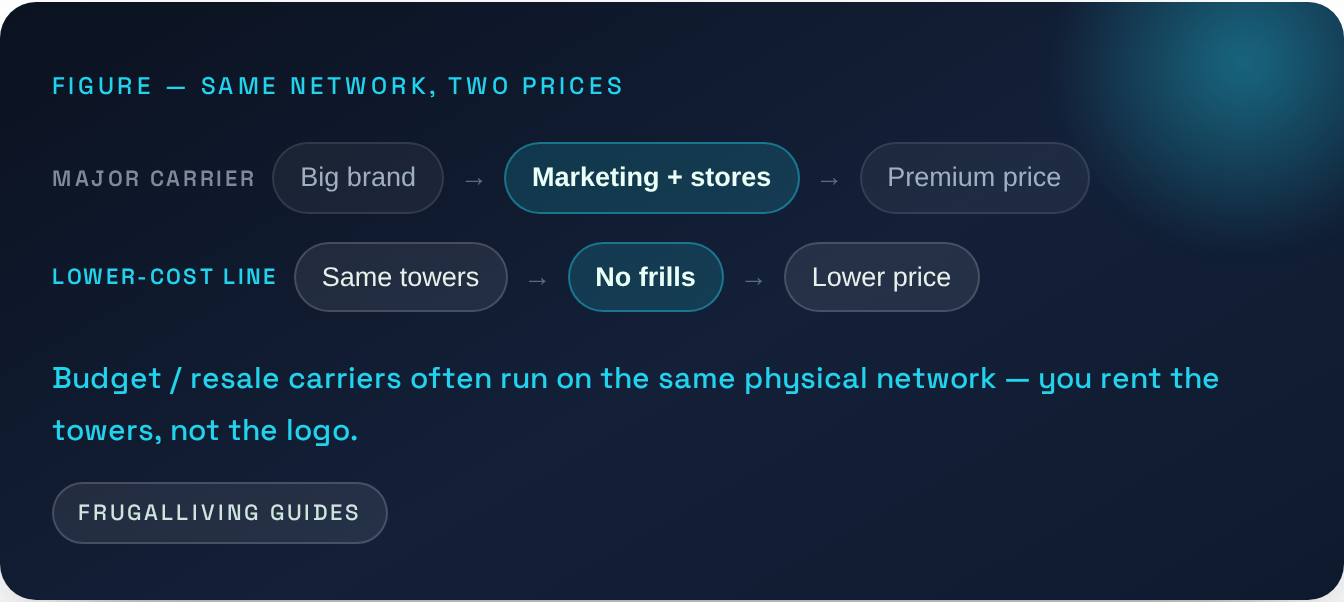
- Compare lower-cost carriers, including MVNOs that use major networks. Coverage can be similar, but priority, roaming, hotspot limits, customer service and congestion policies may differ — compare the details that matter to you.
- Ask whether a lower current plan or retention offer is available. Do not assume the advertised new-customer deal will be matched.
Each useful change lowers a recurring bill without asking you to repeat the decision every day. You do the work once; the lower number repeats on its own.
Read the bill in layers
A phone bill often mixes several different decisions into one total:
- service plan;
- device financing;
- insurance;
- taxes and regulatory fees;
- international or roaming options;
- premium add-ons;
- extra lines, watches or tablets.
That matters because “find a cheaper plan” may not change the bill as much as expected if half the total is a financed device plus add-ons.
Circle the pieces you can actually change.
Compare three months, not one dramatic month
One month can lie.
Travel, a hotspot-heavy week, a home internet outage or a software update can make cellular usage spike. Pull at least three recent months and look for the pattern.
Then ask:
- What was the highest data month?
- How much of the allowance went unused?
- Did anyone on the family plan use hotspot data?
- Are there line-specific add-ons?
- Is a watch/tablet line still needed?
- When does device financing end?
The goal is to right-size the plan without creating a predictable problem next month.
“Same network” does not mean “same experience”
Lower-cost carriers and MVNOs may use the same underlying networks as major carriers, but plan terms can differ.
Compare:
- data priority during congestion;
- domestic and international roaming;
- hotspot allowance;
- video-resolution limits;
- customer support;
- device financing;
- taxes and fees;
- coverage where you actually spend time.
A cheap plan that works at home but fails on your commute is not cheap enough.
Put the re-check on the device-financing end date
Phone bills often stay high because the bill itself became invisible.
When a device payment ends, put a calendar reminder on that month. That is the moment to see whether the monthly total actually falls and whether insurance on an older device still earns its price.
Do the same after a child leaves a family plan, a work phone replaces a personal line, or a travel-heavy season ends.
You’ve plugged the automatic leaks. Now the hard one.
Groceries, utilities, phone — those all leaked on autopilot, and you fixed them by changing defaults. But there’s a category no power strip or plan change touches: the money you actively choose to spend. Next we look at why “choose” is the wrong word for it — and why your brain is running on a timer you didn’t set.
Run the audit once
Pull three months of real usage, compare it with your allowance, price the smaller tiers and any lower-cost providers available on the coverage you need, then remove add-ons you do not use. Recheck after a major usage change or price increase.
Next in this series → Why the Urge to Buy Peaks Before You Own the Thing — what purchase research can actually tell us, without turning dopamine into a cartoon villain.
Part of the larger guide: Why You Can’t Save Money — And the System That Fixes It.
Continue the money-saving cycle
- Previous: Your Electronics Are Still Using Power While “Off”
- Next: Why the Urge to Buy Peaks Before You Own the Thing
Sources & further reading
- Federal Communications Commission, Broadband Consumer Labels — https://www.fcc.gov/broadbandlabels
- FCC, glossary for consumer broadband labels — https://www.fcc.gov/broadbandlabels-glossary
- Federal Communications Commission, consumer resources — https://www.fcc.gov/consumers
- Carrier pricing, network priority, roaming, device financing and plan rules can change. Compare current plan documents before switching.