How to Pay Off Debt in the Right Order
If the goal is to minimize interest, highest-interest-first is the clean mathematical answer. If quick balance closures are what keep you engaged, snowball can be a reasonable trade-off. The important part is knowing what each method optimizes — and when neither simple ranking is enough.
Quick verdict: Keep required minimums current, stabilize essential expenses, choose one target debt, and roll the freed payment forward. Use avalanche for interest efficiency. Consider snowball when visible progress materially improves your ability to stick with the plan.
The two common methods
The CFPB describes two basic debt-reduction approaches.
Highest-interest-first — “avalanche”
Make required minimum payments on the other debts.
Direct extra money to the debt with the highest interest rate.
When that balance is gone, move the extra payment to the next-highest rate.
With otherwise equal payment amounts and timing, this approach attacks the most expensive debt first and can save money over time.
Smallest-balance-first — “snowball”
Make required minimum payments on the other debts.
Direct extra money to the smallest balance.
When that account is paid off, roll its payment into the next-smallest balance.
You may see a complete balance disappear sooner.
The trade-off is that higher-rate balances can keep accruing interest, so the method may cost more overall.
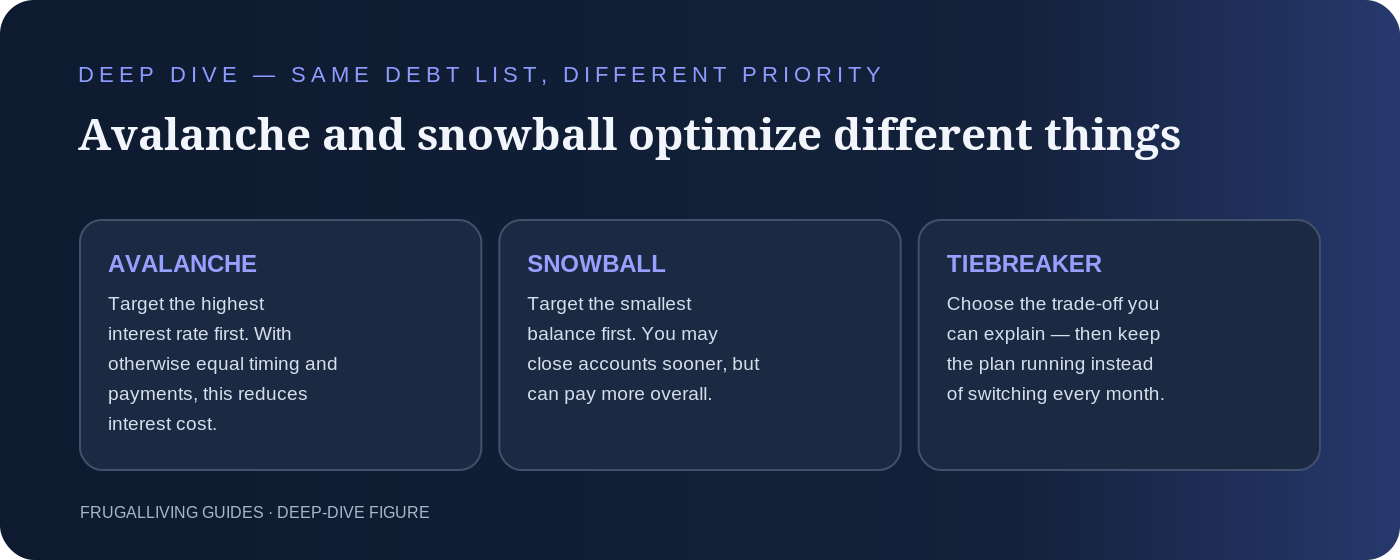
Neither description requires pretending one method is morally superior.
They optimize different things.
Before you choose a method, stabilize the floor
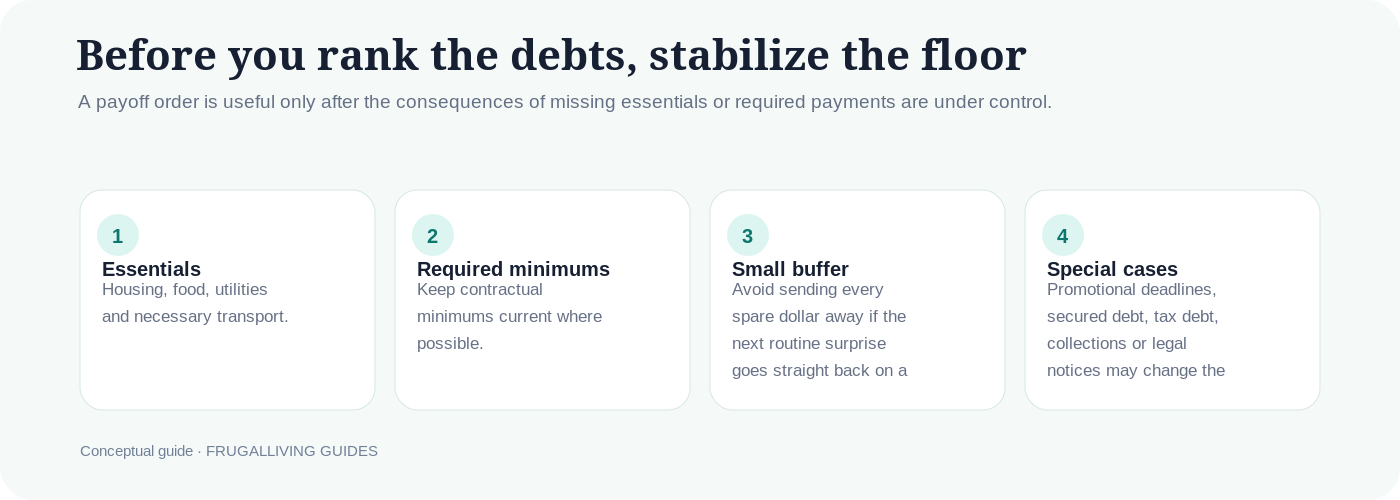
The payoff order matters less if minimums are already slipping or the household cannot cover essentials.
Before accelerating one balance, check:
- housing and essential utilities;
- food and necessary transportation;
- required minimum payments;
- a small amount of liquidity for routine surprises.
This does not mean everyone needs a fully funded emergency account before paying debt aggressively.
It means a payoff plan that sends every available dollar away can be fragile if the next tire, copay or repair immediately goes back on a credit card.
If you are already behind, facing collections, receiving legal notices or considering settlement, a generic ranking article is not enough. Consequences and available options can matter more than APR order.
Which method fits your constraint?
Use avalanche when:
- minimizing interest is the main goal;
- the high-rate target may take time but you can stay with the plan;
- the debt list does not have a special deadline that changes the ranking.
Consider snowball when:
- quick account closures meaningfully improve your persistence;
- you understand that the total interest can be higher;
- the extra cost is an acceptable behavioral trade-off for your situation.
Do not use either method blindly when a balance has unusual consequences.
Examples include:
- a promotional rate that is about to expire;
- debt secured by an essential asset;
- delinquent accounts or collections;
- tax debt;
- court judgments;
- federal or private student loans with special repayment protections or consequences;
- any obligation where a missed deadline matters more than its place in an APR ranking.
A simple example
Suppose the list is:
- $900 at 18%
- $2,800 at 29%
- $6,000 at 8%
Avalanche directs extra money to the 29% balance.
Snowball directs extra money to the $900 balance.
That is the entire philosophical difference in one snapshot.
The next useful step is not to keep debating the method.
It is to choose the order, write it down and redirect the freed payment when a balance reaches zero.
Roll the payment forward
This is the part that makes either method accelerate.
If one debt required a $90 payment and you were sending an additional $160 to it, that target was receiving $250.
When the balance disappears, do not automatically let the entire $250 dissolve back into ordinary spending.
If the household can still afford it, redirect the payment to the next target.
That is how the available debt-payment amount grows as balances close.
Circumstances can change, of course. If income drops or an essential expense rises, the plan may need to be recalibrated.
Do not split extra money by reflex
There are situations where multiple payments make sense.
But if your chosen strategy is avalanche or snowball, the method works by concentrating extra money on the current target while keeping the others current at required amounts.
Sending a little extra to every account can blur the strategy and delay the milestone you selected.
The important distinction is required payments everywhere, chosen extra payment on the target.
Keep the debt list current
At least once a month, record:
- current balance;
- interest rate;
- required minimum;
- promotional rate end date, if any;
- status of the account;
- target order.
That prevents the plan from running on old information.
If a promotional period ends or a variable rate changes sharply, revisit the order.
When speed should not be the only goal
There are times when another use of cash can compete with aggressive debt payoff.
Examples can include:
- a cash buffer that prevents routine expenses from returning to high-cost credit;
- an employer retirement match;
- a looming payment or legal deadline;
- necessary insurance deductibles or essential repairs.
This is why the larger money system matters.
Debt is one priority inside a household, not a morality test that automatically outranks every other risk.
Choose the plan you can explain
A good debt plan should fit in one sentence.
“I am paying the highest rate first because minimizing interest is my priority.”
or
“I am paying the smallest balance first because quick closures materially help me keep going, and I accept the potential extra interest.”
If you can explain the trade-off, you are choosing a method.
If you are changing the order every week because one balance feels emotionally louder, you are re-deciding.
Choose once.
Review when the facts change.
Next in this series → How Much Emergency Fund Do You Actually Need?
Part of the larger guide: The FrugalLiving Money System.
Sources & further reading
- Consumer Financial Protection Bureau — How to reduce your debt
- CFPB — Reducing debt worksheet
- CFPB describes highest-interest-first as the method that can save money over time and snowball as the method that may create quicker visible progress while costing more overall.
- Generic payoff ordering is not individualized advice for delinquent, secured, tax, student-loan, collection or legally disputed debt.